

Payactiv
by On-demand pay and beyond
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
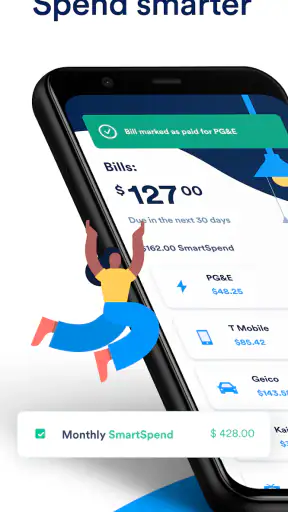
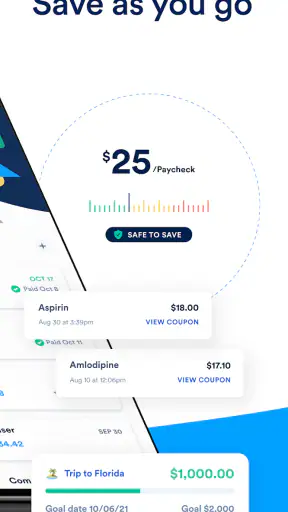
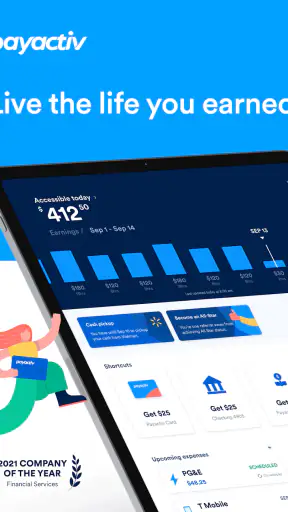
 Analysis by Getfullapps
When money is tight between paydays, the problem is often not poor planning but timing. A bill arrives, a car needs fuel, or a grocery trip cannot wait for the next payroll deposit. I reviewed Payactiv as a finance app built around that gap, and I found its most useful idea easy to understand: it connects eligible earned wages with a person who needs access before the normal payday. The important word is “eligible,” because the experience depends heavily on how your employer’s payroll setup works.
Payactiv is free to download and is rated for Everyone, which makes it approachable for a wide range of users. It comes from the developer On-demand pay and beyond, has been available since June 4, 2014, and has grown to over one million installs. Its average rating is 4.4 from around forty-five thousand ratings, so it is clearly not an obscure experiment. I would describe it as a practical cash-flow tool rather than a complete banking replacement or a magic solution for recurring debt.
Following a real Payactiv workflow from a shortfall to a payday
I find it helpful to judge Payactiv as a sequence of handoffs, not just a button for accessing wages: first the app must connect your work and payroll information, then the amount has to match a real need, and finally the money must arrive in time to matter. Following that chain also makes it easier to spot where a delay or mismatch could change your plan, which leads naturally into the next section.
Starting with the actual problem
The best way to judge this app is to imagine a normal situation. Suppose I have worked several shifts, but my regular paycheck is still days away. A utility payment is due now, and using a credit card would either create a balance I cannot clear quickly or add interest to an already difficult month. In that situation, Payactiv may offer a more direct route than borrowing from a friend, applying for a new credit product, or waiting for overdraft protection to cover the expense.
That does not mean I would open the app every time I wanted extra spending money. The sensible use is tied to wages I have already earned, not income I merely expect to receive. This distinction is central to responsible use. If the app becomes a routine way to make an unaffordable budget appear workable, the convenience can hide the underlying problem. I see the strongest case when the need is temporary and specific, such as transportation to work, an urgent household purchase, or a bill that falls awkwardly before payday.
Before relying on it, I would first check whether my employer participates and whether my employment and payroll details can be matched successfully. That is the first handoff in the process: Payactiv cannot independently turn any job into an on-demand wage source. The employer and payroll connection determine whether the app can see the information needed to calculate access to earned pay.
Setting up the account without treating it like a normal wallet
The initial setup feels different from opening a general budgeting app. I would expect to provide enough personal and employment information for the service to connect me with the correct workplace record. Accuracy matters here. A mismatch in a name, employer detail, or payroll identity can create friction that has nothing to do with the quality of the app itself.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is also where I would slow down and read every screen concerning delivery, eligibility, and any applicable costs before confirming a transfer. “Free” refers to the app’s price, not a promise that every possible transaction route is costless. A responsible review cannot treat early wage access as identical to receiving a standard paycheck. The practical question is what I will receive, when I will receive it, and whether the chosen delivery method has conditions attached.
My advice is to complete setup before an emergency happens. Installing a financial app during a stressful evening, with a payment deadline approaching, is a poor time to discover that an employer connection needs attention. A calm setup lets me verify the account, understand the available options, and decide whether the service is useful before I am under pressure.
Checking the amount instead of guessing
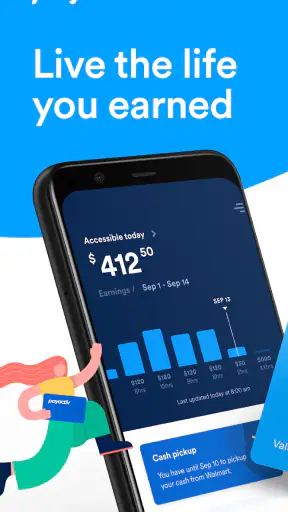
Once the connection is working, the next step is understanding what amount is available. I would not assume that every hour worked is immediately transferable or that the full amount of a future paycheck can be requested. The figure shown in the app should be treated as a current, calculated availability amount, not as a promise about total monthly income.
This is one of the less obvious strengths of an earned-wage workflow: it encourages me to separate money already generated from money that still depends on future shifts. That can improve a decision. If I need only enough to cover a small shortfall, requesting the smallest practical amount is safer than taking the maximum simply because it appears on screen.
I would also compare the timing with the urgency of the expense. If a bill can wait until the ordinary payday, the normal payroll route may be simpler. If the payment must happen today, early access may justify the extra step. The app is most useful when timing is the problem; it is less compelling when I am merely looking for a more convenient place to store money.
Choosing the handoff to the destination
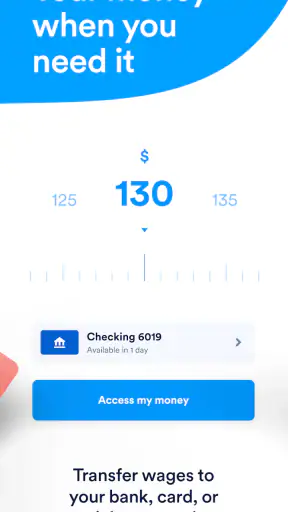
The request does not end when I tap for access. There is a handoff from the app to the selected destination, and that handoff is where expectations matter most. I would check whether the money is going to a bank account, card, or another supported route shown in my own account, then confirm the timing and any conditions displayed before submitting.
Delivery speed should not be confused with guaranteed instant availability in every circumstance. Processing can depend on the route, account details, employer data, and the time of the request. For that reason, I would not initiate a transfer minutes before a critical deadline unless the app clearly confirms the expected arrival. A tool designed for urgent cash flow still requires a small amount of planning.
This is also a point where Payactiv differs from a conventional budgeting app. A budgeting app helps me decide where money should go, while this service focuses on when earned money becomes accessible. They can work together, but they solve different problems. I would use a budget to prevent repeated shortfalls and Payactiv only when the timing gap remains after that planning.
Understanding the payroll handoff
The most important handoff happens later, when the early access is reconciled with the normal payroll process. I would think of the amount as an advance on wages already earned, not as a separate bonus. The regular paycheck must still reflect what has already been accessed, so I would keep a record of the transfer and avoid treating the next payday as if it were untouched income.
This is where a user can make an avoidable mistake. If I withdraw money early and then spend as though my full paycheck is still coming, the next pay period may feel unexpectedly small. My practical habit would be to note the amount in my budget immediately, assign it to the original need, and reduce the expected payday balance by the same amount. That simple accounting step is more valuable than repeatedly checking an available balance.
The employer is part of this process even when the user interacts mainly with the app. Payroll information, work records, and the eventual paycheck all sit in the background. If a shift is missing, employment status changes, or payroll information is delayed, the amount shown may not match what I expect. I would contact the appropriate support channel rather than repeatedly submitting requests or assuming the app has lost money.
What the outcome looks like in everyday use
In the best-case scenario, the workflow is straightforward: I identify a genuine shortfall, confirm that the wages are available, choose a delivery method, receive the money in time, and account for the adjustment at payday. That outcome can be much less disruptive than carrying a high-interest balance for a small temporary expense.
The app also aims beyond one transfer by presenting financial wellness as part of the experience. I would treat that area as useful only if it leads to a concrete habit: tracking the reason for each early request, building a small buffer, or planning bills around the actual payroll calendar. Advice has value when it changes what I do next month; otherwise, the transfer function remains the only part I am really using.
For someone paid on a predictable schedule, the result may be relief rather than financial improvement. Payactiv can move the timing of access, but it does not increase total earnings. That nuance matters. It can solve “I need my earned money before Friday,” but not “my income is permanently lower than my essential expenses.” In the second situation, a conversation with an employer, a debt counselor, or a broader budgeting change is more appropriate.
Three practical habits that make the workflow safer
First, I would create a specific purpose before requesting anything. “Cover the electricity bill” is a workable purpose; “have more money available” is too vague. A named expense makes it easier to stop once the need is met and reduces the chance of spending the transfer casually.
Second, I would compare early access with the cost of the alternative, not just with the emotional relief it provides. If waiting is harmless, waiting may be better. If the alternative is a late fee or expensive revolving debt, the calculation changes. The right choice depends on the actual consequence of delay, not on the app’s convenience alone.
Third, I would keep the app out of the role of emergency savings. Even if access is reliable for my employer, I would still aim to build a separate reserve. A reserve is available without depending on current payroll records, eligibility calculations, or a delivery handoff. Payactiv can bridge a gap, but a reserve removes the gap.
Where the flow breaks down
The biggest limitation is eligibility. Someone whose employer is not supported, whose payroll information cannot be matched, or whose work data has not updated may reach the app and still be unable to use its central function. This is not a minor inconvenience because early wage access is the reason most people would install it.
Another friction point is expectation management. Users may assume that “earned wages” means every recent hour is immediately available, that every request arrives instantly, or that the next paycheck will feel normal afterward. Those assumptions can produce frustration even when the service is operating as intended. I would read the in-app details carefully and plan around the confirmed result rather than an idealized one.
I would also skip Payactiv if I wanted a full-featured everyday bank account, a broad investing platform, or a replacement for disciplined money management. Its purpose is narrower. Someone who needs spending categories, long-term savings tools, or detailed account aggregation may be better served by a dedicated personal finance app alongside ordinary banking services.
Privacy and account security deserve the same attention as with any finance tool. I would use a strong, unique password, keep the phone protected, and avoid completing setup on a shared device. Those are ordinary precautions, but the app deals with employment and income information, so casual handling would be a mistake.
Who should use it and who should choose another route
I think Payactiv is a good fit for an employee with a participating employer, variable expenses, and an occasional gap between work completed and payday. It is particularly practical when the alternative is a costly short-term borrowing option and the requested amount can be tied to a specific, necessary expense.
I would be more cautious if my income is already insufficient every month. Early access can make the current week easier while making the next payday harder, creating a repeating cycle. In that case, a traditional bank account with a clear budget, an emergency fund plan, or direct help with debt and bills may produce a better long-term result.
Compared with an overdraft facility, Payactiv is conceptually cleaner when the money is based on wages already earned rather than a negative account balance. Compared with a payday loan, it may avoid the feeling of taking on an entirely new debt, but I would still examine the exact terms and payroll impact instead of assuming every early-access transaction is automatically harmless. Compared with a standard savings account, it offers speed rather than a cushion; the two should not be treated as substitutes.
My conclusion after following the whole process
Payactiv makes the most sense when I view it as a controlled bridge from completed work to the next scheduled paycheck. The app is free, accessible to Everyone, and established enough to have over one million installs, with a 4.4 average from around forty-five thousand ratings. Its current version is 2.2.8 and requires an operating system version of at least 10, details worth checking before installation.
My recommendation is conditional but positive: use it when the employer connection works, the need is real, and the amount requested is small enough to fit comfortably into the next payroll cycle. Set it up before an emergency, confirm the delivery details, record the transfer in a budget, and treat financial-wellness guidance as a prompt for better habits rather than a substitute for them.
Payactiv is strongest as a timing solution, not an income solution. If that distinction matches your situation, it can be a genuinely useful addition to your financial toolkit. If you need lasting relief from expenses that exceed your pay, I would choose a broader plan instead of relying on repeated early access.
Pros
- Early access to earned wages can help cover urgent expenses.
- Supports bill payments and money transfers within the app.
- Offers budgeting tools to help track spending and plan ahead.
- May include discounts and financial wellness resources for members.
- Available through participating employers without a traditional credit check.
Cons
- Access depends on your employer’s participation in Payactiv.
- Fees may apply for instant transfers or certain financial services.
- The amount available depends on hours already worked and employer data.
- Some features may vary by employer, location, or account type.
- Not a replacement for long-term budgeting or emergency savings.
FAQs for Payactiv
What is Payactiv, and how does it work?
Payactiv is a financial wellness app that can give eligible employees access to part of their earned wages before the regular payday. After connecting through a participating employer, the app displays available earnings based on hours already worked. Users may transfer funds to a bank account, debit card, or use supported payment options, depending on employer setup and location.
Who can use Payactiv?
Payactiv is generally available to employees whose employers offer Payactiv as part of their workplace benefits. Eligibility, available balance, transfer limits, and supported features can vary according to the employer’s payroll system, work schedule, and local regulations. If your employer does not participate, downloading the app alone may not provide access to earned wage services.
Does Payactiv charge fees for using the service?
Payactiv may offer some access and transfer methods at no cost, while other options can involve a transaction fee. The exact pricing depends on your employer’s plan, the type of transfer selected, and the destination account or card. Before confirming a transaction, review the fee details shown in the app so you understand the total cost.
How quickly can I receive money through Payactiv?
The delivery time depends on the transfer method you choose. Some supported cards or accounts may receive funds quickly, while standard bank transfers can take longer, particularly outside business hours, on weekends, or during holidays. Payactiv also relies on employer payroll data, so your available balance may not update immediately after every shift.
Is Payactiv safe to use, and what should I know before signing up?
Payactiv uses account verification and security measures designed to protect personal and financial information, but users should still follow basic safety practices. Download the official app, use a strong unique password, enable available security features, and never share login or verification codes. Read the privacy policy and employer-specific terms before linking a bank account or card.

Payactiv
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via payactivadmin@payactiv.com, visit https://www.payactiv.com/, or review their https://www.payactiv.com/privacy-policy/.










